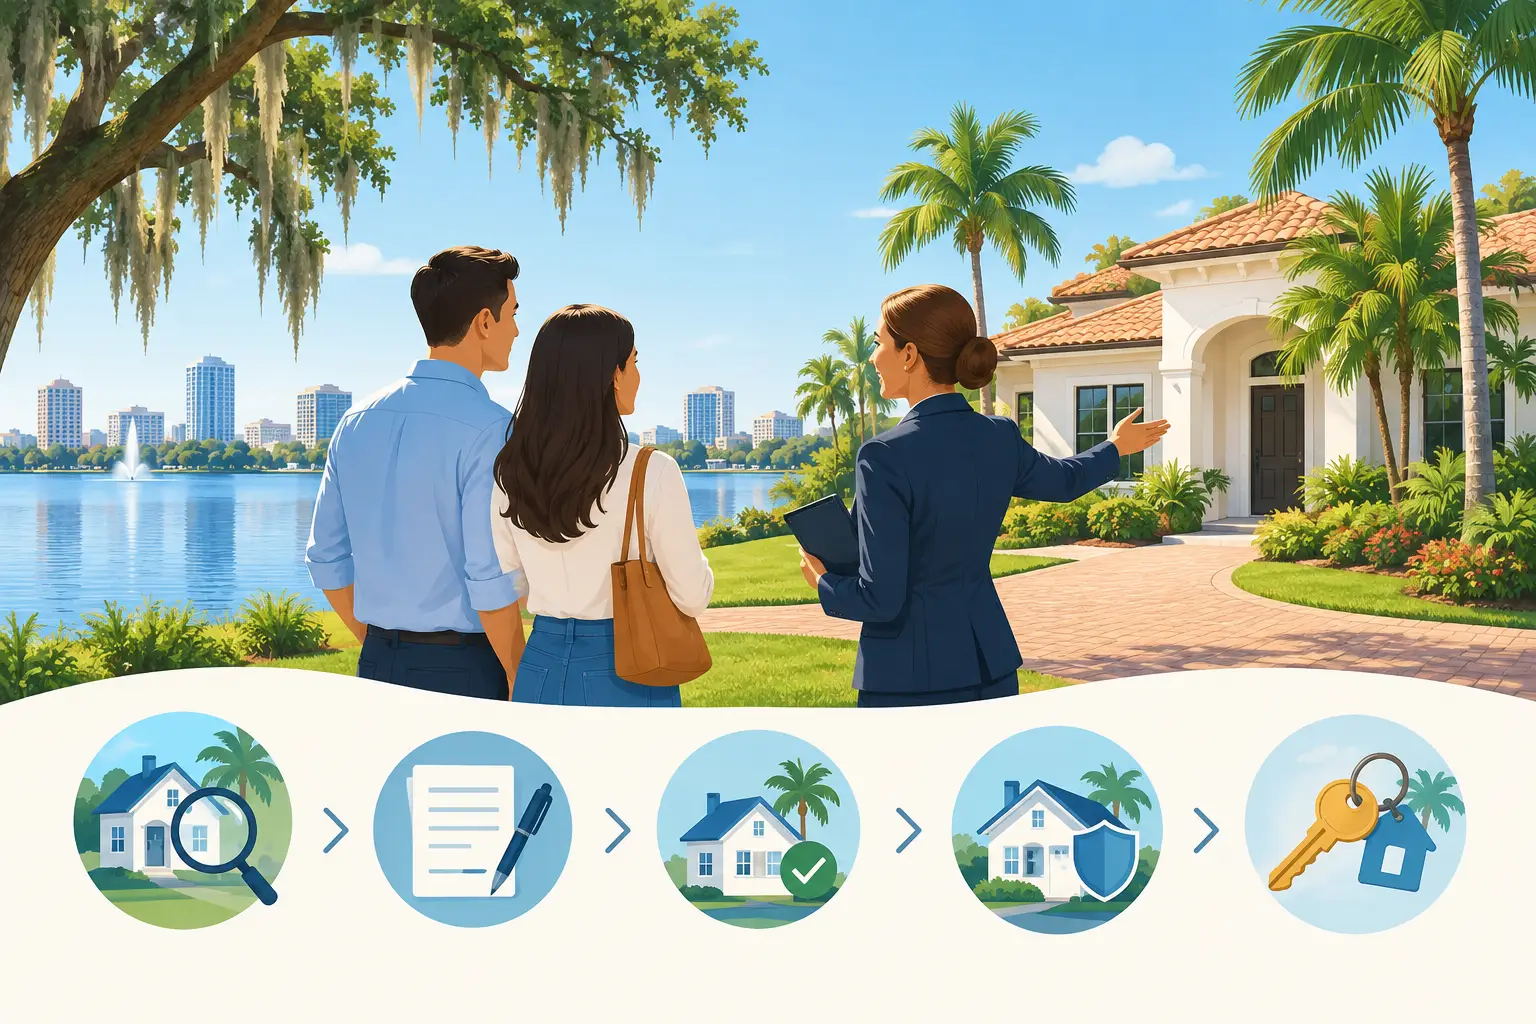
A home search can move quickly in Central Florida. A well-priced property in a desirable Orlando neighborhood may receive several offers before the first weekend is over, while another home can sit because its condition, location, or price misses the mark. The Orlando home buying process works best when you make financial decisions early, narrow the areas that truly fit your life, and evaluate each property with a clear plan.
For buyers relocating from another state, the process has an added layer: you are not simply choosing a house. You are choosing commute patterns, schools, flood exposure, insurance costs, access to parks and dining, and a community that will still make sense if your needs change. A local Realtor should help you assess all of those factors before you are under contract.
Start the Orlando Home Buying Process With a Real Budget
Your target price is only one part of the budget. Before scheduling a full day of showings, speak with a qualified lender and obtain a current preapproval. This gives you a realistic purchase range and shows sellers that you are prepared to perform when you make an offer.
A lender will review income, assets, debts, credit, and the type of financing you plan to use. The preapproval should also account for monthly obligations beyond principal and interest, including property taxes, homeowners insurance, mortgage insurance when applicable, and homeowners association dues. Florida insurance costs deserve particular attention. They can vary substantially based on a property’s age, roof condition, proximity to water, prior claims history, and construction features.
Do not assume that every home at the same price will carry the same monthly payment. A newer townhome with an HOA may have different insurance responsibilities than an older detached home in an established neighborhood. A condominium may have association fees, rental restrictions, and reserve considerations that require additional review. Looking at the complete payment early prevents an avoidable disappointment later.
Keep Cash Reserves Separate From Your Down Payment
In addition to your down payment, plan for earnest money, inspections, lender fees, title and closing charges, prepaid insurance, and moving expenses. The exact amount depends on your loan, contract terms, and the property, but buyers should avoid putting every available dollar into the down payment if that leaves no room for repairs or the unexpected.
In Florida, the seller may contribute toward certain buyer closing costs if the contract and loan guidelines allow it. That can be valuable, but it should not be treated as a substitute for reviewing the overall price, property condition, and loan terms.
Choose Communities Before Choosing a Floor Plan
Orlando is not one housing market. A buyer who wants walkability, older architecture, and proximity to downtown may look differently at College Park or Winter Park than a buyer focused on newer construction, larger lots, or an easier route to major employment centers. Dr. Phillips, Baldwin Park, Lake Nona, Windermere, Winter Garden, Lake Mary, Longwood, and Oviedo each present different trade-offs in lifestyle, inventory, price range, and commute.
For relocation buyers, online photos and map pins only go so far. A 20-minute drive at noon can be considerably different during a weekday commute. A neighborhood that looks ideal on a listing portal may be near a busy road, flight path, school pickup line, or commercial development that changes the day-to-day experience.
Start with the factors you cannot easily change: commute tolerance, school preferences, proximity to family or work, lot size, home style, and budget. Then separate true requirements from preferences. A pool, renovated kitchen, three-car garage, or gated entrance may be important, but being too rigid can eliminate strong homes that offer better location, condition, or resale appeal.
Use Local Comparisons, Not Broad Averages
Median sale prices and market headlines can be useful background, but they do not establish value for a specific home. Value is shaped by recent comparable sales, square footage, lot characteristics, updates, condition, school zoning, HOA requirements, and competition among current listings.
This is especially relevant in neighborhoods with mixed housing ages or varied renovation levels. Two homes on the same street can command very different prices because one has a newer roof, updated plumbing and electrical systems, hurricane-impact features, or a more functional layout. A property search should be followed by a close comparison of what has actually sold, not just what is currently being advertised.
Tour Homes With the Inspection in Mind
When you walk through a home, look beyond staging and finishes. Ask about the age of the roof, HVAC system, water heater, windows, plumbing, and electrical panel. Observe drainage around the home, the condition of exterior paint and soffits, signs of moisture, and whether additions appear properly integrated into the original structure.
Florida homes often require a more detailed conversation about systems and environmental conditions. A home does not need to be new to be a good purchase, and an older home can offer excellent construction and character. Still, the cost and timing of major components should be part of the decision, particularly when insurance underwriting may require information about the roof, electrical, plumbing, or HVAC.
Condominium and townhome buyers should also review association documents carefully. Monthly fees, rental rules, pet policies, parking, assessments, maintenance responsibilities, and financial reserves can affect both your ownership experience and future resale. If the association is responsible for exterior maintenance or roofing, understand what that coverage includes and what owners may still need to insure themselves.
Make an Offer That Matches the Property and Competition
A strong offer is more than the highest number. It is a complete package that considers price, financing, down payment, earnest money, inspection period, closing timeline, appraisal contingency, and seller priorities. The best approach depends on the home.
If a property has just come on the market in a high-demand area and is priced appropriately, waiting for a price reduction may not be realistic. If a home has been available for several weeks, shows deferred maintenance, or has comparable sales that do not support the list price, a more measured offer may be appropriate. The goal is not to win at any cost. It is to secure the right property on terms you understand.
Your agent should explain the likely strengths and risks of each strategy before you sign. Waiving protections simply to appear aggressive can create unnecessary exposure. At the same time, an offer with overly broad contingencies may be less attractive to a seller even when the price is competitive. Good negotiation requires a clear reading of the property, the seller’s situation, and the current market response.
What Happens After Your Offer Is Accepted
Once a contract is signed, deadlines begin. Earnest money is delivered according to the contract, the lender receives the executed agreement, inspections are scheduled, and the title process starts. This is where responsive communication matters most.
A general home inspection is customary, and additional inspections may be warranted depending on the property. Buyers may choose inspections for wood-destroying organisms, pool equipment, roof condition, sewer lines, mold, or other specific concerns. The purpose is not to expect a perfect report. Nearly every home, including newer construction, will have findings. The useful question is whether the findings are routine maintenance, manageable repairs, material safety concerns, or expensive issues that change the value equation.
If significant items arise during the inspection period, your options depend on the contract and the facts. You may request repairs, seek a credit, renegotiate, accept the property as-is, or cancel within the applicable contingency period. The appropriate choice depends on the nature of the issue, local contractor availability, insurance implications, and how the home compares with alternatives.
Appraisal, Loan Approval, and Title Review
For financed purchases, the lender orders an appraisal to support the collateral value for the loan. An appraisal is not a home inspection, and a home inspection is not an appraisal. If the appraisal comes in below the contract price, the buyer and seller may renegotiate, the buyer may bring in additional funds if permitted and desired, or the transaction may end if a contingency applies.
Meanwhile, underwriting verifies your financial information and reviews property-related requirements. Avoid opening new credit accounts, making large unexplained deposits, changing jobs, or buying furniture on credit before closing. Even a financially sound buyer can create delays by making changes that affect debt, available cash, or verification requirements.
The title company examines ownership records, coordinates payoff information when needed, and prepares documents for closing. Review all disclosures and closing figures promptly. If anything is unclear, ask before the appointment rather than trying to resolve a question at the closing table.
Close With a Plan for the First Month
Before closing, complete a final walkthrough to confirm the property is in the agreed condition, requested repairs have been addressed if applicable, and included items remain in place. The walkthrough is not a second inspection, but it is an important final check.
After closing, arrange utilities, confirm insurance coverage, change locks or rekey the home, and keep your inspection report and repair records organized. For a move to Orlando, give yourself time to learn the practical details that do not appear on a listing: preferred routes, local service providers, seasonal maintenance, and how the neighborhood functions on an ordinary weekday.
The right home purchase is rarely the result of rushing to the first attractive listing. It comes from practical preparation, property-level analysis, and direct guidance from someone who knows the Central Florida market. Will LaValle provides that one-to-one support, helping buyers make decisions they can feel comfortable living with long after the closing day.
Explore Winter Park area neighborhoods
Winter Park · Maitland · Baldwin Park · Longwood · Lake Mary · What’s my home worth?